In a nutshell
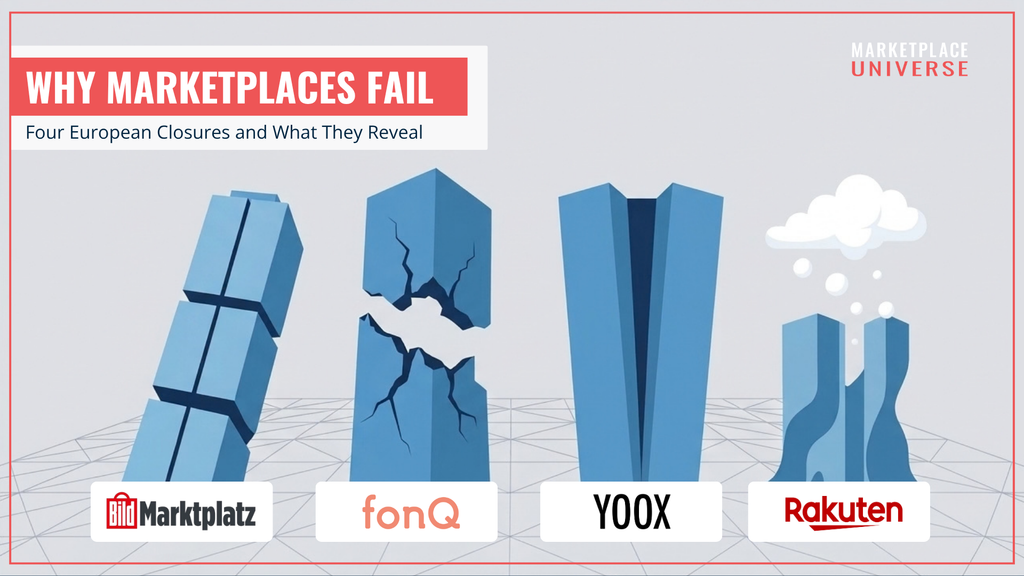
Four European marketplaces collapsed between 2024 and 2026. Each failure had a different root cause. This article examines the structural patterns that separate thriving marketplaces from those destined to fail.
⏱ Time to Read: appr. 9 min
BILD Marktplatz: Speed Without Strategy
On 2 September 2026, Axel Springer’s BILD Marktplatz closed without announcement. Two years after launch, the German media giant had built a marketplace on an assumption that proved catastrophically wrong: that audience reach translates to marketplace revenue.
The numbers tell the story. BILD.de reaches approximately 30 million daily readers — among the highest-traffic news outlets in Europe. When the marketplace launched in March 2024, it started with 30,000+ articles from 50+ sellers. The timeline was aggressive: 11 weeks from decision to go-live. “Don’t overthink it, just do it — BILD-style,” marketplace lead Sten Kolod said during a 2024 Mirakl Platform Summit panel discussion.
But the speed masked a fundamental structural gap: the assortment strategy was explicitly deferred. The team launched first and planned to develop product strategy later, based on how readers and sellers reacted. Many of the 30,000 articles showed near-zero stock or were sold out at launch. The link between BILD.de and the marketplace barely existed.
Over two years, no real assortment strategy ever emerged. The marketplace never capitalised on BILD.de’s massive reach, and Axel Springer appeared to treat it as a peripheral project rather than a core strategic asset. As Marketplace Universe co-founder Ingrid Lommer observed in her LinkedIn analysis of the marketplace: “speed without a sourcing or assortment concept doesn’t shift risk to the platform, it shifts it to the sellers who invest in integration and inventory on a platform that hasn’t decided what it wants to be. That’s degrading seller partners to beta-testers without compensation.”
The core problem: Axel Springer had audience reach but no marketplace strategy. Without a coherent assortment strategy from launch, the platform remained undefined. Two years in, it was still trying to figure out what it wanted to sell..
fonQ and Naduvi: When M&A Cannot Fix Structural Weakness
In March 2024, fonQ — an established Dutch online furniture and home retailer founded in 2003 — acquired Naduvi, a boutique Amsterdam-based interior design outlet marketplace founded in 2019. The idea seemed sound: merge the marketplace model with the retail retailer to create operational synergy.
The integration was catastrophic. By March 2026, the combined entity filed for bankruptcy. By May 2026, both sites were offline.
The acquisition itself was not the disease — it was a symptom. According to Itai Gross, Naduvi’s founder, fonQ was already failing before the merger. “The vulnerability was within the fonQ organisation itself, not the merger,” Gross stated. “fonQ had been heavily loss-making for a long time.” The integration was a rescue attempt, and it actually improved operational performance temporarily — but the deeper problem remained unchanged.
The structural mismatch was not between two incompatible businesses but within the category itself. Home and living is a logistics-intensive, thin-margin market dominated by Amazon (scale), IKEA (owned inventory control), and Temu/AliExpress (volume pricing). Merging a quality-focused retailer with curated inventory against a marketplace aggregating 250+ brands at discount prices created operational complexity — two inventory systems, two logistics networks, conflicting vendor relationships — but it couldn’t solve the fundamental problem: neither model generates sufficient margins to sustain both cost structures in this category.
The acquisition was a pivot away from a failing retail model toward marketplace economics. It worked operationally but could not overcome category economics. Once shareholder funding stopped, the combined entity had no independent defensibility.
👉 Marketplace Universe Insight: Acquisitions cannot fix category economics. When two businesses merge to solve a structural problem but the underlying category cannot support either cost model, the merger becomes a compression of failure, not a path to recovery.
YOOX: When Hybrid Models Cannot Defend Margins
YOOX.com was an Italian off-price luxury fashion retailer owned by Yoox Net-a-Porter Group (YNAP) — a conglomerate of luxury brands that included the original Net-a-Porter (a curated 1P luxury retailer), YOOX (its off-price affiliate), and other holdings. On the surface, the numbers looked strong. According to ECDB retailer profile data, YOOX.com was recording:
- €59.1 million monthly GMV
- 236,000 monthly buyers
- €190.44 average order value
Yet the company was posting losses exceeding €1 billion annually. That was the problem: not weak revenue but unsustainable costs.
The root issue was architectural. YOOX tried to operate as both a curated, off-price retailer carrying its own inventory AND as a 3P marketplace aggregating external sellers. This meant warehousing, write-downs, direct logistics, buyer’s-market risk — all the operational costs of a retailer — while simultaneously managing vendor relationships and collecting marketplace commissions. At €59.1 million monthly GMV in off-price luxury, the margin structure could never justify those dual cost structures.
The constant restructuring reveals the distress. In 2024, Mytheresa (a Berlin-based luxury e-commerce retailer) acquired the insolvent YNAP parent company. By September 2025, Richemont (the Swiss luxury conglomerate that owned YNAP through Cartier, Van Cleef & Arpels, and other brands) decided to merge YOOX with another platform. By December 2025, LuxExperience (a new entity) acquired YOOX separately. The restructuring was not about growth but about survival. And it failed.
Rakuten France: Two Decades Without Understanding the Market
Rakuten France — formerly PriceMinister — operated as a second-hand and refurbished goods marketplace for 16 years under ownership by Rakuten Group (a Japanese e-commerce and fintech conglomerate with operations across retail, fintech, telecom, and content).
The 16 years masked a deeper failure: Rakuten spent nearly two decades trying to establish itself across Europe without ever successfully understanding either the European market structure or European consumer behaviour. The company had gradually withdrawn from most European countries well before the final France exit. In 2025, announcing a Spain expansion seemed like a strategic restart. Eight months later, in July 2026, Rakuten announced it would close the French marketplace by year-end.
The narrative blamed competition or market saturation. The reality was organisational: Rakuten never built the operational knowledge to compete in Europe on European terms. Marketing campaigns that worked in Japan failed in Europe. The generalist positioning that made sense in Asia didn’t gain traction against the established players.
Once Rakuten Group shifted capital expenditure toward fintech, telecommunications, and content platforms, the France marketplace was reclassified as non-core and allocated no further investment. But the decision to exit was not a surprise strategic shift — it was the conclusion of a long pattern of European underperformance that the company had never solved.
This reveals a core truth: 16 years of operational history cannot overcome fundamental market misalignment. Marketplace success requires not just capital and time, but genuine understanding of the market you’re in. Once the parent company deprioritised the investment, there was no independent defensibility because the marketplace had never achieved it.
The Patterns: Structural Forces, Not Execution Failure
These four failures span different categories, geographies, and business models. Yet each reveals a distinct structural trap that goes beyond execution or market timing.
| Marketplace | The Pattern | The Outcome |
|---|---|---|
| BILD | No coherent assortment strategy from launch. Platform never decided what to sell or to whom. Speed replaced strategic clarity. | Launched with 30,000 articles, many out of stock. Two years in, still undefined. Audience reach could not substitute for marketplace operations. |
| fonQ/Naduvi | Acquisitions in structurally different category economics create integration debt faster than synergy. Two different cost structures cannot be merged profitably. | Attempted to merge retailer model with marketplace model in furniture category. Losses accumulated faster than synergies could materialize. |
| YOOX | Hybrid models (own inventory + 3P marketplace) try to defend two incompatible margin structures simultaneously. | €59.1M monthly GMV but €2B+ accumulated losses. Retailer costs + marketplace commissions = unsustainable economics. |
| Rakuten France | Failed to understand European consumer behaviour and market structure across nearly two decades. Generalist positioning incompatible with European market dynamics. | Gradually exited European countries before final France withdrawal. 16 years of operations could not overcome fundamental market misalignment. |
👉 Marketplace Universe Insight: BILD did not fail because a competitor entered the market. YOOX did not fail because it faced more efficient players. fonQ did not fail because bol existed. Each failed because its underlying model was fundamentally misaligned with category economics.
Key Learnings
- Reach without operations DNA is a liability. BILD’s 30 million daily readers converted to only 32,000 marketplace buyers. Media traffic and commerce traffic occupy different psychological spaces. Audience reach alone has zero correlation with marketplace GMV.
- M&A should only happen within compatible category economics. fonQ and Naduvi were in the same category but had incompatible cost structures. Integration costs exceeded synergies because the category itself cannot support the combined overhead.
- Choose one model, not two. YOOX tried to be both a curated retailer and a 3P marketplace. The accumulated loss of €2 billion on €59.1 million monthly GMV proves the hybrid cannot defend margins against specialists operating one model only.
- Scale and history are vulnerable to parental priority shifts. Rakuten’s 16 years in France and €2.4 billion group-level GMV were insufficient when the parent company deprioritised the marketplace. Without ongoing capital expenditure commitment, scale becomes irrelevant.
01.10.2026 – Written by Ricarda Eichler, Journalist and Author for OHN